
[CoreWeave, AI Crisis Trigger ③] Lessons from the 2008 Financial Crisis

 Prefer us on Google



Recurrent financial crises... The 2008 case
Small defaults turn into massive risks
Is the AI bubble about to burst? Managing debt risk is key
[Block Media Reporter Lee Jeong-hwa] The reason why bets on credit default risks instill fear in financial markets can be well understood by looking at the example of the 2008 global financial crisis. At that time, U.S. financial institutions engaged in large-scale subprime mortgage lending to borrowers with low credit ratings.
While individual home mortgage loans were small in scale, financial institutions bundled thousands of loans to create mortgage-backed securities (MBS).
Here, a more complex financial product emerged. Financial institutions re-bundled mortgage-related securities to create collateralized debt obligations (CDOs), dividing them into various grades based on the order in which investors would bear losses. Even if high-risk loans were included, lower grades could be assigned high credit ratings by establishing a subordinate grade that would bear losses first.
What happens when you add risk to risk?
With the combination of credit default swaps (CDS), the risks became even more complicated. Investors purchased CDS to hedge against the default risk of mortgage-related bonds. Conversely, insurance companies and financial institutions sold CDS and received premiums.
The problem was that investors who did not actually hold the bonds could also bet on the defaults of mortgage bonds through CDS. Products like synthetic CDOs further replicated the credit risks of existing mortgage bonds using CDS. Even if the underlying asset, home mortgage loans, did not increase, more financial contracts could be created based on the same credit risk.
As U.S. housing prices fell and delinquencies and defaults on subprime loans surged, the value of related securities plummeted. Financial institutions that had sold CDS faced massive losses and demands for additional collateral.
A representative case is the American insurance company AIG. AIG provided guarantees for large-scale credit derivatives, but as the mortgage market worsened, the value of contracts fluctuated dramatically, increasing the pressure to provide additional collateral. This burden, combined with other investment losses, led AIG into a liquidity crisis, ultimately requiring a bailout from the U.S. government. Lehman Brothers, which did not receive a bailout, went bankrupt. Lehman was the largest investment bank on Wall Street dealing with CDOs and CDS at the time.
The causes of the financial crisis were not solely due to CDS. A combination of bad loans, excessive leverage, inaccurate credit ratings, complex securitization structures, and interconnections between financial institutions played a role. However, it is clear that CDS and synthetic credit products expanded risk exposure among financial institutions and complicated the pathways for loss transmission.
Investor George Soros criticized CDS as a destructive financial product after the financial crisis.
AI Debt of $450 Billion... Similarities and Differences with 2008
Recently, the AI industry has also seen an expansion of investments based on large-scale borrowing. According to Bloomberg, the amount of AI-related debt issued in the global bond market exceeded $450 billion in 2026.
Large tech companies like Alphabet, Amazon, Meta, and Microsoft are investing massive amounts of money to build AI data centers and semiconductor infrastructure. These companies have high credit ratings and significant cash generation capabilities, but as the scale of investment has grown unprecedentedly, some companies have seen their free cash flow turn negative.
Financial institutions have also increased lending and bond acquisitions for AI-related companies, raising the need to manage credit risk. Banks buy CDS to reduce credit risk exposure to specific companies, while hedge funds sell CDS to pursue premium income.
According to the International Swaps and Derivatives Association (ISDA), the global CDS trading volume is expected to reach $41.8 trillion by 2025, the highest ever recorded. This figure reflects the trading volume and does not equate to the actual outstanding risk amount or expected loss amount. The increase in AI-related CDS trading indicates that there is a simultaneous rise in demand to transfer credit risk and investors willing to assume it.
It is currently difficult to equate the AI financial market with the 2008 subprime crisis. In 2008, the crisis centered around home mortgage loans from households with weak repayment abilities and complex securitization products.
In contrast, a significant portion of current AI-related borrowing is occurring among large tech companies with high credit ratings and cash generation capabilities. Moreover, the mere increase in CDS trading does not provide grounds to conclude that a synthetic CDO structure similar to that of 2008 has been widely established in the AI market.
The risks currently identified are more directly linked to the economic viability of AI facility investments, excessive borrowing, and funding burdens due to rising interest rates.
Nevertheless, there is an important commonality between the two periods. Large-scale borrowing is being undertaken based on the expectation that future asset values will continue to rise and that investment demand will be maintained.
In 2008, the belief in rising housing prices collapsed. In the current AI market, the key variable is whether investments in data centers and high-performance semiconductors can generate sufficient cash flow.
CoreWeave's Warning... "The Crisis is in the Bond Market"
CDS is not a product that directly causes corporate defaults. However, it reflects the rising credit risk in market prices and plays a role in transferring risks between financial institutions. Especially if a CDS seller assumes large-scale credit risks without sufficient collateral or capital, the shock of a corporate default could spread to counterparties.
The case of AIG in 2008 demonstrated this counterparty risk.
This is why the sharp rise in CoreWeave's CDS premiums cannot be viewed merely as a speculative price fluctuation. Of course, just because CDS premiums have surged does not mean that this will immediately lead to a financial crisis. It must be judged separately whether warnings about credit risk will lead to actual defaults or a chain of losses among financial institutions.
What the market needs to confirm going forward are CoreWeave's debt maturity and refinancing capabilities, the cash generation capacity of AI data centers, the risk burden size of CDS sellers, and the concentration of credit risk among financial institutions.
Even if AI technology grows in the long term, not all infrastructure investors can bear the cost of funding. The 2008 financial crisis demonstrated that the belief in the growth potential of assets and the safety of the financial structure supporting it are two different issues.
The sharp rise in CoreWeave's CDS premiums also raises the same question. Just because the future of AI looks bright does not mean that the debt accumulated to invest in that future is 100% safe.
-- Price
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
Arthur Hayes Reveals Altcoin Selection Logic, Emphasizes Accumulating Bitcoin
Vitalik, Tom Lee, Arthur Hayes and Others Share Views on Cryptocurrency and AI
Multiple Theft Incidents Fund Flow into ZEC, Attackers Use It to Transfer Stolen Funds
Pago Móvil Reaches 63% of Transactions in Venezuela, Competing with USDT
Analysts Bullish on MicroStrategy, Target Price Raised to $240
Bank of America Report Shows $39 Billion Inflow into US Stocks in One Week, Strategists Prefer Risk Aversion
MSCI New Rules Implemented, 14 Crypto Companies Enter Potential Impact List
What Do the New Tesla Roadster Specs Mean for Tesla (TSLA) Stock?
Explore the new Tesla Roadster specs, reservation payments and 2028 production plan, plus what the reveal could mean for Tesla stock and future profits.
Quant (QNT) Price Prediction 2026–2030: Can Bank Adoption Drive a Return to $500?
Spout raises $2M to offer 0% interest loans on Solana
RWA Weekly: Ant Group and HSBC Test Agent Tokenized Payments; Robinhood Explores Tokenized Actively Managed ETFs
BlackRock CEO Larry Fink Flags a Different AI Risk, and It Isn’t the Bubble
Shanghai Supports International Data Center Construction to Facilitate Cross-Border Data Flow
Shanghai Advances National Blockchain Network Construction, Strengthens Cross-Chain Service Capabilities
When Will AI Investments Pay Off? JPMorgan Optimistic About Google and Amazon
What is being said at the tables: the BCRA turns on the dollar vacuum and the city counts the bullets in Javier Milei's bazooka
New Developments in the Blue Sky Ge Rui Case: Bitcoin Rises 200 Times, Can Victims Only Be Compensated at Original Price?
Bitcoin inflows to US set to turn positive in 2026, Chainalysis says
iGaming Tokens Need Real Revenue, Not Just Hype
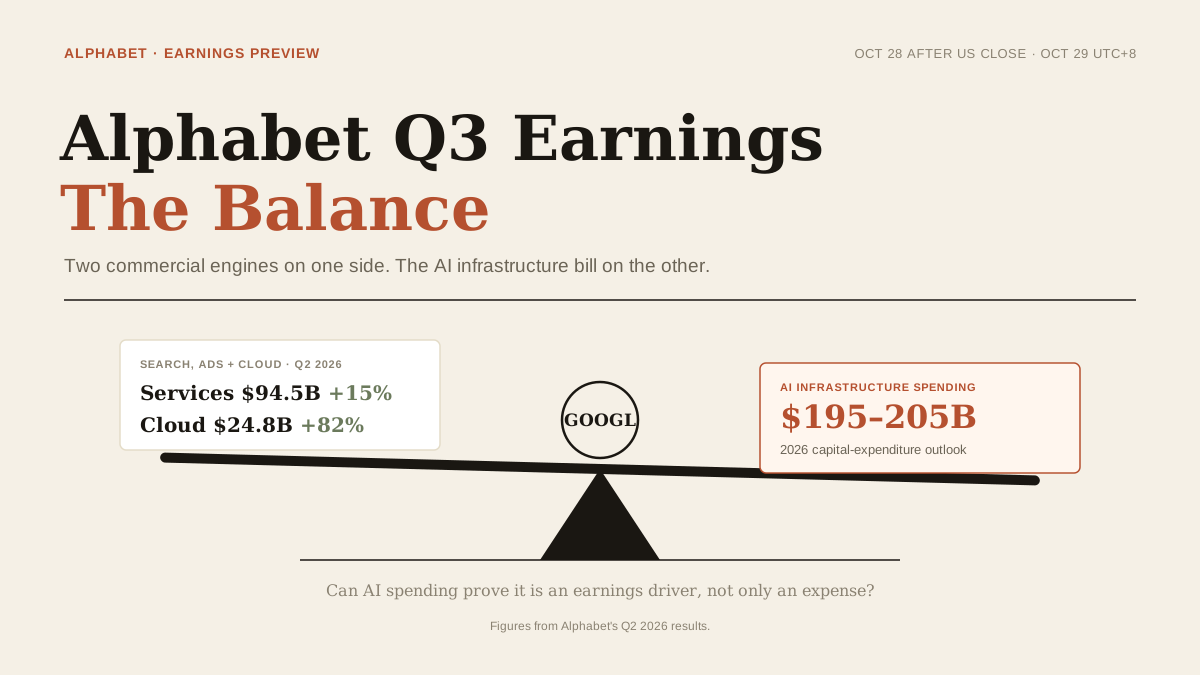
Google Stock Before Alphabet Earnings: Can AI Spending and Search Growth Support GOOGL?
Alphabet reports Q3 2026 results on October 28. See the Search, Google Cloud, AI spending, and guidance signals shaping GOOGL stock.
Fractional Reserve: Reserve Requirement Abolished. Where is the Value?
Anthropic's Revenue Rises to $16.8 Billion Ahead of IPO
‘Is Korea Facing a Second IMF Crisis? The Solution Lies in XRP?’... The Leap of the Crisis Theory by BeInCrypto
ICO, VC Tokens, and Alpha Models: Why They Can't Save the Current Crypto Market?
One Order Book for Dollars and Stablecoins. How It Works
Cyberattack on the ports of Marseille and La Rochelle? Hackers paid 1 dollar in crypto
[Exclusive] Coinbase Transaction Data Shows 100 Million Trades Misrepresented... Data Analysis Firm Corrects Errors
Wall Street Morning Report: U.S. Inflation Resurfaces, AI Credit Risks Spread, Chip Stocks Fall for Six Consecutive Days
Arthur Hayes: Focus on Established DeFi Projects with Cash Flow
Anthropic Reports $16.8 Billion Revenue in Q3, IPO Feasibility Strengthened
Arthur Hayes Reveals Altcoin Selection Logic, Emphasizes Accumulating Bitcoin
Vitalik, Tom Lee, Arthur Hayes and Others Share Views on Cryptocurrency and AI
Multiple Theft Incidents Fund Flow into ZEC, Attackers Use It to Transfer Stolen Funds
Pago Móvil Reaches 63% of Transactions in Venezuela, Competing with USDT
Analysts Bullish on MicroStrategy, Target Price Raised to $240
Bank of America Report Shows $39 Billion Inflow into US Stocks in One Week, Strategists Prefer Risk Aversion


