
FOMC Minutes Take Center Stage as ADI Drive the Next Validation Round for AI Hardware | WEEX Weekly Market Preview (August 17-August 21, 2026)

 Prefer us on Google


Key Themes This Week
This week’s macro focus is less about backward-looking inflation prints and more about whether the Fed minutes and high-frequency growth data can reshape rate expectations heading into September. On the industry side, earnings from optical module manufacturing, test and measurement, analog semiconductors will help determine whether AI capex momentum is still broadening across the supply chain. If the minutes lean hawkish and PMI data remains resilient, markets may reprice a “firm growth, delayed easing” backdrop; if the tone is more balanced and corporate guidance holds up, growth equities could retain room for valuation repair.
August 17 | Monday
Fabrinet Q4 and FY2026 Results | ★★★★☆
As a key manufacturing partner in high-end optical communications and precision photonics, Fabrinet’s results should provide an early read on AI data-center optical module demand, component utilization, and upstream capacity conditions. If orders, utilization, and management guidance improve in tandem, the market may gain further confidence that the AI optical chain has not materially cooled after the second quarter.
Potential Trading Instruments:
Optical Manufacturing: FNON-USDT
August 18 | Tuesday
Keysight FY2026 Q3 Results | ★★★☆☆
Keysight’s earnings will serve more as a midstream validation point, with investors watching whether advanced test and measurement demand continues to benefit from AI server, networking, and semiconductor R&D spending. Stronger orders and guidance would reinforce the view that AI infrastructure spending is extending beyond GPUs into system verification and broader hardware enablement.
Potential Trading Instruments:
Test and Measurement: KEYSON-USDT
August 19 | Wednesday | Key Trading Day
FOMC July Meeting Minutes | ★★★★★
The key issue in this release is not simply the Fed’s inflation language, but the degree of internal divergence over the policy path and the durability of U.S. growth. A hawkish set of minutes could push long-end Treasury yields and the U.S. dollar higher, tightening valuation conditions for growth assets; a more neutral tone could allow risk assets to extend their consolidation recovery.
Potential Trading Instruments:
Nasdaq Exposure: QQQB-USDT
Analog Devices FY2026 Q3 Results | ★★★★☆
The market will focus on whether demand remains durable across industrial, data-center, power management, and edge-AI exposure. If the analog cycle recovery and AI-linked contribution improve at the same time, semiconductor leadership could broaden further from compute leaders into analog, power, and industrial automation names.
Potential Trading Instruments:
Analog Semiconductors: ADION-USDT
August 20 | Thursday
Walmart FY2027 Q2 Results | ★★★★☆
Walmart’s quarterly results matter beyond retail alone, as they offer an important lens into U.S. consumer resilience, e-commerce penetration, and the expansion of higher-margin businesses such as advertising and membership. If the revenue mix continues shifting toward e-commerce, membership, and ad monetization, the market may grow more comfortable with the view that the U.S. consumer slowdown remains contained.
Potential Trading Instruments:
U.S. Consumer Bellwether: WMTON-USDT
August 21 | Friday
U.S. August Flash PMI | ★★★★☆
Friday’s U.S. Flash PMI will be one of the week’s most important high-frequency growth indicators, shaping views on whether the U.S. economy remains in expansion and whether price pressures are reaccelerating. If both activity and price components surprise to the upside, the market may lean further into a “resilient growth, later easing” scenario; a softer print would help ease upward pressure on yields.
Potential Trading Instruments:
Nasdaq Exposure: QQQB-USDT
Trading Roadmap This Week
Macro: FOMC minutes will shape whether rate expectations tilt more hawkish again, while U.S. Flash PMI will help validate the direction of global liquidity and growth resilience.
AI: Fabrinet, Keysight, and ADI will test whether AI capex continues to broaden across optical communications, test equipment, and analog semiconductors.
Consumer and Risk Appetite: Walmart’s results will provide an important read on U.S. consumption quality and platform-style retail profitability, influencing how confidently the market embraces the soft-landing narrative.
-- Price
This content is provided for general informational purposes only and doesn't constitute financial, investment, legal, or tax advice. Any events, rewards, online promotions, or related information mentioned herein should not be considered a recommendation, solicitation, or invitation to purchase, sell, trade, or otherwise deal in any crypto assets. Crypto assets are highly volatile and may result in loss. The availability of WEEX services, products, and related events may vary by region. You are responsible for ensuring that your participation is in accordance with applicable local laws and regulations.
You may also like
WEEX Exclusive:FOMC Minutes Take Center Stage as ADI Drive the Next Validation Round for AI Hardware | WEEX Weekly Market Preview (August 17-August 21, 2026)
PCE and Micron Drive Rate Trades| WEEX Weekly Market Recap (September 28-October 2, 2026)
WEEX Weekly Market Recap focuses on PCE, payrolls, JOLTS job openings, OpenAI DevDay, The AI Conference, Micron earnings, Accenture earnings, Bitcoin Treasuries Conference, and the NEAR Intents security incident. The week’s core narrative centered on rate-path repricing, AI order validation, AI memory demand, and crypto security risk.
Oil Supply Premium Lifts Energy Stocks| WEEX TradFi Daily (October 2, 2026)
Markets on October 2 are focused on oil, long-end yields and payroll data. Major equity indexes closed slightly higher on October 1 after being pressured intraday by a spike in long-end yields, with AI and energy helping support risk appetite. Accenture (ACN) jumped after AI-related bookings, revenue and full-year guidance topped expectations, while Nike (NKE) fell after hours on weaker sales. Brent crude broke above $102 and energy stocks strengthened. Bitcoin traded near $83,500. Markets are also digesting the NEAR Intents security incident and expectations for Monad’s privacy-service reveal.
Micron’s Strong Guidance Meets Long-Bond Pressure|WEEX Market (October 1, 2026)
Markets on October 1 are focused on long-end yields, consumer earnings and consulting earnings. August PCE rose 3.4% year over year and core PCE 3.0%, both below forecasts, while implied odds of another policy-rate hike fell to about 36%. Still, the 10-year Treasury yield climbed to about 5.29%, a high since 2007, keeping pressure on long-duration risk assets. Micron beat on results and next-quarter guidance, but the after-hours gain was limited. Bitcoin traded near $83,600. Investors now watch jobless claims at 08:30 ET, Accenture before the open and Nike after the close.
30-Year Yield Hits a High Since 2002| WEEX TradFi Daily(September 30, 2026)
Markets on September 30 are focused on long-end yields, inflation data and memory earnings. Major equity indexes closed lower on September 29. The 30-year Treasury yield topped 5.61% intraday, its highest level since June 2002, and closed near 5.59%, keeping pressure on long-duration growth valuations. OpenAI is reportedly discussing a funding round of at least $30 billion at a target valuation of about $1.4 trillion; OPENAI futures spiked and then faded pre-market, trading near $1,628 at the source snapshot. Brent fell to about $96, WTI was near $89, and Bitcoin was around $83,500. ADP data are due at 08:15 ET and August PCE at 08:30 ET; Micron’s after-hours report will test the memory cycle and AI demand.
10-Year Yield Breaks 5%| WEEX TradFi Daily(September 29, 2026)
Global markets on September 29 focused on the 10-year yield breaking above 5% and Anthropic’s IPO filing. On September 28, all three major equity indexes closed lower, with semiconductors and optical communications among the sectors that retreated. Anthropic’s filing showed high growth alongside large losses and $518 billion in cloud commitments. Its tokenized share traded near $2,002, down about 2% in 24 hours. Spot gold approached a two-month low near $4,118, while Bitcoin traded near $83,500.
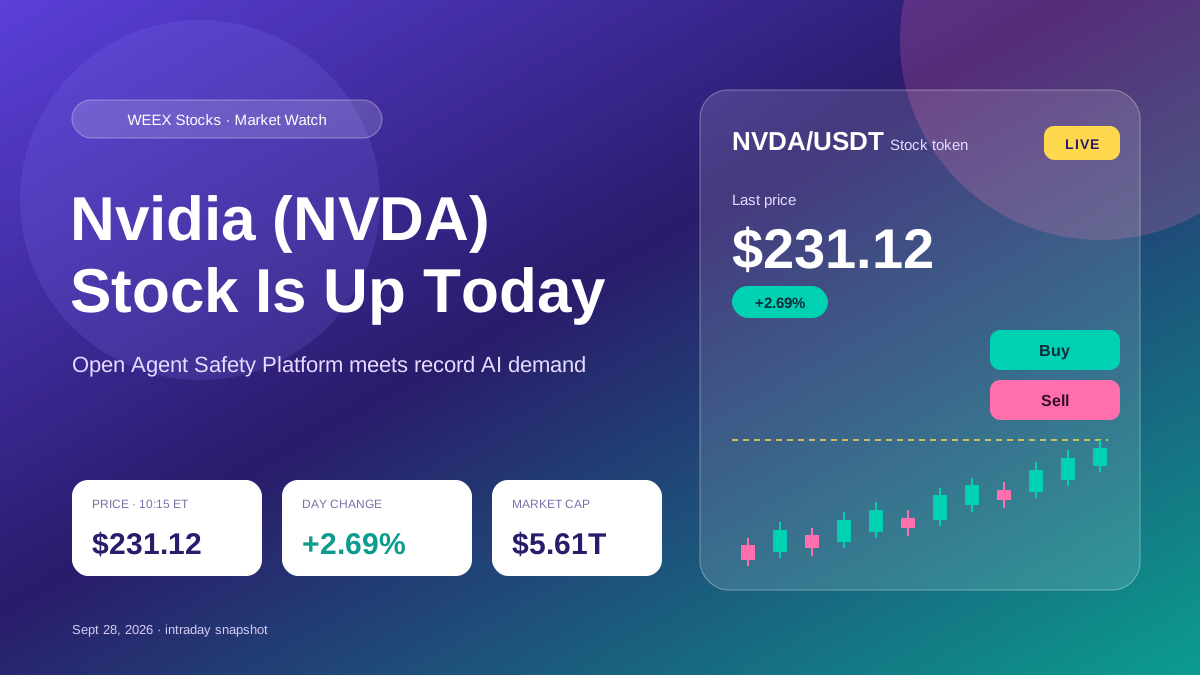
Why Is Nvidia (NVDA) Stock Up Today? New AI Agent Safety Platform Fuels the Rally
Why is Nvidia stock up today? Explore the AI agent safety launch, Nvidia’s growth outlook, key risks and how the NVDA token works on WEEX.
PCE Set the Tone This Week | WEEX TradFi Daily Brief (September 28, 2026)
Global markets on September 28 enter a data and earnings window. On September 25 ET the S&P 500 rose 0.51% to 7,743.41, the Nasdaq 0.48% and the Dow 0.93%. Information technology and semiconductors outperformed; energy lagged as oil eased. The 10-year yield is about 5.15% and the 30-year about 5.5%, with October hike odds around 64%–66%. Bitcoin last traded near $84,500. Investors wait on September 30 ET PCE and Micron guidance.
PCE and Payrolls are coming |WEEX Weekly Market Hotspot (September 28-October 2, 2026)
ONDO Tokenized Smart-Portfolio Narrative Builds| WEEX TradFi Daily Brief (September 25, 2026)
Global markets on the morning of September 25 Beijing time focus on rate pricing and a split in AI infrastructure. On September 24 ET the S&P 500 was near 7,704 and almost unchanged, the Nasdaq edged higher and the Dow fell 0.31%. The 10-year yield rose to about 5.18% and the 30-year to about 5.47%. Bitcoin last traded around $84,400.
Oracle Stock vs. KRAFTON Stock: Why Are Investors Questioning Two Growing Companies?
Compare Oracle and KRAFTON stocks through their latest results, share-price questions and the different growth tests investors face in 2026.
Bitcoin Pulls Back From $87,000| WEEX TradFi Daily Brief (September 24, 2026)
Bitcoin pulled back from about $87,000 to about $84,000, with Ethereum near $2,680. S&P Global PMI on September 23 ET far exceeded forecasts. The 10-year yield broke above 5.00%, while the 5-year and 30-year touched highs last seen in 2007 and 2004. The S&P 500 and Nasdaq slipped. Energy moved with oil and crypto-treasury stocks followed bitcoin lower. Investors await earnings from COST, BB, and others.
CME Plans BCH and UNI Futures on October 19 | WEEX TradFi Daily Brief (September 23, 2026)
Global markets on September 23 focus on a Nasdaq high and an expansion of crypto futures. The Nasdaq closed higher on September 22 for a second straight closing high. Memory names such as Micron and SanDisk plus AI hardware lifted risk appetite. Brent eased to about $98 and WTI to about $94.6. Bitcoin was near $86,200 and Ethereum near $2,750. Investors are watching CME’s planned October 19 BCH/UNI futures and the impact of delayed compute-futures review on NVDA and CME.
AMD Jumps Nearly 10%, Market Cap Tops $1 Trillion| WEEX TradFi Daily Brief (September 22, 2026)
Global markets on September 22 focus on a repair in AI-compute pricing. On September 21 the three major equity indexes closed higher. AMD rose nearly 10% and its market cap crossed $1 trillion for the first time, while Intel and Arm also surged. Brent crude fell about 3.4% to $100.34 and the 10-year Treasury yield eased to about 4.96%, lowering discount-rate pressure on long-duration tech. Bitcoin briefly broke above $87,000 and total crypto market cap returned above $3 trillion. Investors next watch consumer and housing earnings plus PMI flash prints.
Leaders’ Summit Take Focus | WEEX Weekly Hotspot Preview (September 21-September 25, 2026)
WEEX Weekly Market Hotspot Preview focuses on activity data, policy-maker remarks, Flash PMI, a leaders’ summit, durable goods orders, final consumer sentiment readings, and earnings from Costco. The week’s core narrative centers on rate-path repricing, growth resilience, summit-driven risk premium, and consumer fundamentals.
Bitcoin Reclaims $81,000| WEEX TradFi Daily Brief (September 21, 2026)
Global markets enter the trading week of September 21, with core pricing still centered on the rate path after the Fed's 25 bps hike on September 16 to 3.75%–4.00%, as well as consumer and energy pricing. Bitcoin stands above roughly $81,000 and Ethereum has rebounded to about $2,630, suggesting that the rate hike and regulatory disruptions have been partially digested. NEAR is up about 19% in 24 hours, leading major coins. No blockbuster earnings are due on September 21 ET; investors turn to speeches from officials including Goolsbee, the Chicago Fed National Activity Index, and consumer leaders such as AutoZone starting Tuesday and Costco on Thursday.
SEC Tokenized-Stock Exemption Lands| WEEX TradFi Daily Brief (September 18, 2026)
Global markets rebounded strongly on September 17 ET after digesting the hike. On September 16 ET the Fed raised rates 25 basis points to 3.75%–4.00%, and the dots showed 16 of 18 officials expect at least one more hike this year. The three major U.S. indexes all closed higher, led by chips and crypto treasury stocks. The same day, regulators launched an innovation exemption for tokenized stocks, lifting UNI, ONDO and Robinhood-chain names. Investors are watching October hike pricing.
Fed Hikes 25 bp, Pressuring Risk Assets as ZEC Rallies Toward $1,360 | WEEX TradFi Daily Brief (September 17, 2026)
Global markets re-priced after the September 16 ET Fed hike. The policy rate was raised 25 basis points to 3.75%–4.00%. Chair Walsh stressed that inflation remains high and another hike this year is possible. The three major U.S. indexes closed lower. Bitcoin traded $75,000–$76,500, gold fell, and crude stayed above $100 but declined on the day. Capital is focused on the hike path, after-hours housing guidance and a new high in privacy coin ZEC.
CLARITY Vote Fails; Bitcoin Breaks Below $76,000 | WEEX TradFi Daily Brief (September 16, 2026)
Global markets on September 16 are focused on the Fed rate decision. On September 15, the S&P 500 fell 0.45% to 7,585.73, the Nasdaq fell 0.78%, and the Dow fell 0.63% as the 10-year yield broke above 5% and Brent crude rose to about $109. The CLARITY procedural vote failed to clear the 60-vote threshold, sending bitcoin down to about $75,600 and Ethereum toward $2,400. Energy led with a gain of about 2.3%. Investors are waiting for the 14:00 ET policy statement and Walsh press conference on September 16.
AI Slowdown Push Weighs on Chip Stocks; FOMC in Focus | WEEX TradFi Daily Brief (September 15, 2026)
Fed September Meeting Takes Center Stage | WEEX Weekly Market Preview (9.14-9.18, 2026)
Bitcoin Falls to $77,000; FOMC in Focus This Week | WEEX TradFi Daily (September 14, 2026)
Ahead of the September 14 open, global markets are focused on this week’s FOMC. After hotter-than-expected August inflation, odds of a September 16 hike rose above about 85%. Bitcoin broke below $77,000 to about $76,700–$76,800, with Ethereum near $2,500. In Friday’s session, communication services and industrials outperformed, while Apple closed up about 1.75%. CrowdStrike (CRWD) drew attention after unveiling AI-agent protection products at Fal.Con, and investors are also waiting for this week’s key CLARITY Act procedural vote and the rate decision.
August CPI to Lock In Next Week’s Hike Pricing | WEEX TradFi Daily(September 11, 2026)
Global markets on September 11 focus on August CPI. Brent crude holds $100–$107, the 10-year yield jumps first to about 4.94%, and hike odds are pushed to about 70%–74%. On September 10 ET the S&P 500 fell 0.58%, the Nasdaq 0.65% and the Dow 0.60%. Bitcoin broke below $77,000 and Ethereum slipped near $2,440; gold and silver also came under pressure. This is a liquidity squeeze, not an internal crypto blow-up. Apple shares recovered after its foldable launch, and AeroVironment bounced after hours on a beat.
How Will Apple's New Product Launch Event Impact AAPL Stock and Stock Tokens?
Oil Back Above $100 | WEEX TradFi Daily (September 10, 2026)
On September 10, markets digested Apple’s product event and the oil breakout. Apple (AAPL) launched its first foldable iPhone Duo at $1,999, while the iPhone 18 Pro price rose by $100 to start at $1,199. The stock closed down about 0.3% at $315.34 on September 9 ET. Brent crude moved back above $100, all three major U.S. indexes closed lower, and energy was the only sector to post a gain of about 1.1%. Bitcoin remained capped by renewed hike pricing. Investors are now waiting for Adobe (ADBE) and Oracle (ORCL) earnings after the close on September 10 ET.
Apple Foldable Event Nears | WEEX TradFi Daily(September 9, 2026)
Global markets are focused on Apple’s fall product event, firmer energy prices, and the renewed valuation pressure on risk assets. Apple shares retreated ahead of the launch as investors weighed foldable-device pricing, on-device AI monetization, and potential sell-the-news volatility. Energy equities benefited from supply-risk repricing, which also reinforced sticky-inflation concerns and a higher-for-longer rates narrative. In crypto, bitcoin eased toward the mid-$78,000 range; although spot ETF inflows remain supportive, positioning has turned more defensive in the face of rising hike expectations. After the close, AeroVironment earnings and Apple’s product details could shape the next move across tech and thematic trades.
Oracle and Adobe in Focus This Week |WEEX TradFi Daily (September 8, 2026)
Markets are entering a new pricing window after the U.S. holiday close, with attention shifting squarely to this week’s catalysts. Stronger August payrolls revived expectations for a more restrictive Fed path and pushed yields higher, weighing on long-duration equities. In crypto, bitcoin eased below $80,000, but continued spot ETF inflows suggest institutional demand remains supportive at lower levels. At the same time, AI meme tokens materially outperformed the broader market, showing that speculative capital is still concentrating in high-beta thematic trades. Investors are now watching GME earnings, Oracle and Adobe results, and the upcoming PPI and CPI prints for the next repricing signal.
Inflation Data and Oracle Earnings Take Center Stage | WEEX Weekly Hotspot Preview (September 7-11, 2026)
This week’s WEEX Weekly Market Hotspot Preview focuses on the September 7 Labor Day holiday, Crypto Expo Dubai 2026 on September 9-10, the U.S. August PPI and Oracle FY2027 Q1 earnings on September 10, and the U.S. August CPI plus the Deribit BTC/ETH weekly options expiry on September 11. The core market narrative centers on inflation repricing, validation of enterprise AI-cloud demand, the return of post-holiday liquidity, and a reassessment of short-term crypto volatility.
Payrolls Beat Revives Hike Pricing | WEEX TradFi Daily(September 7, 2026)
Global markets spent the weekend digesting last week’s payrolls data and crypto fund flows. August job growth of roughly 162,000 and a steady 4.1% unemployment rate pushed the 10-year Treasury yield to around 4.78%, reviving rate-hike pricing and weighing on technology and other long-duration assets. In crypto, bitcoin held near $80,000 as spot ETF inflows remained supportive, signaling that institutional risk appetite has not fully faded. At the same time, oil stayed firm on Middle East supply concerns, while gold consolidated at elevated levels. This week, attention turns to Oracle and Adobe earnings, as well as CPI, for the next repricing of the September Fed path.
Bitcoin Back Above $81K, Payrolls in Focus | WEEX TradFi Daily(Sept. 4, 2026)
Today’s market narrative was shaped by a recovery in crypto risk appetite and a deeper extension of the AI investment theme. Bitcoin moved back above $81,000 as macro pressure eased at the margin, while NVIDIA’s acquisition of Hugging Face underscored the strategic shift from compute dominance toward control of model ecosystems and developer access points. At the same time, results from Snowflake and Ciena reinforced that AI spending is spreading from semiconductors into software and network infrastructure. Near term, the August U.S. payrolls release is likely to be the key catalyst for rates expectations and valuation direction across growth assets.
WEEX Exclusive:FOMC Minutes Take Center Stage as ADI Drive the Next Validation Round for AI Hardware | WEEX Weekly Market Preview (August 17-August 21, 2026)
PCE and Micron Drive Rate Trades| WEEX Weekly Market Recap (September 28-October 2, 2026)
WEEX Weekly Market Recap focuses on PCE, payrolls, JOLTS job openings, OpenAI DevDay, The AI Conference, Micron earnings, Accenture earnings, Bitcoin Treasuries Conference, and the NEAR Intents security incident. The week’s core narrative centered on rate-path repricing, AI order validation, AI memory demand, and crypto security risk.
Oil Supply Premium Lifts Energy Stocks| WEEX TradFi Daily (October 2, 2026)
Markets on October 2 are focused on oil, long-end yields and payroll data. Major equity indexes closed slightly higher on October 1 after being pressured intraday by a spike in long-end yields, with AI and energy helping support risk appetite. Accenture (ACN) jumped after AI-related bookings, revenue and full-year guidance topped expectations, while Nike (NKE) fell after hours on weaker sales. Brent crude broke above $102 and energy stocks strengthened. Bitcoin traded near $83,500. Markets are also digesting the NEAR Intents security incident and expectations for Monad’s privacy-service reveal.
Micron’s Strong Guidance Meets Long-Bond Pressure|WEEX Market (October 1, 2026)
Markets on October 1 are focused on long-end yields, consumer earnings and consulting earnings. August PCE rose 3.4% year over year and core PCE 3.0%, both below forecasts, while implied odds of another policy-rate hike fell to about 36%. Still, the 10-year Treasury yield climbed to about 5.29%, a high since 2007, keeping pressure on long-duration risk assets. Micron beat on results and next-quarter guidance, but the after-hours gain was limited. Bitcoin traded near $83,600. Investors now watch jobless claims at 08:30 ET, Accenture before the open and Nike after the close.
30-Year Yield Hits a High Since 2002| WEEX TradFi Daily(September 30, 2026)
Markets on September 30 are focused on long-end yields, inflation data and memory earnings. Major equity indexes closed lower on September 29. The 30-year Treasury yield topped 5.61% intraday, its highest level since June 2002, and closed near 5.59%, keeping pressure on long-duration growth valuations. OpenAI is reportedly discussing a funding round of at least $30 billion at a target valuation of about $1.4 trillion; OPENAI futures spiked and then faded pre-market, trading near $1,628 at the source snapshot. Brent fell to about $96, WTI was near $89, and Bitcoin was around $83,500. ADP data are due at 08:15 ET and August PCE at 08:30 ET; Micron’s after-hours report will test the memory cycle and AI demand.
10-Year Yield Breaks 5%| WEEX TradFi Daily(September 29, 2026)
Global markets on September 29 focused on the 10-year yield breaking above 5% and Anthropic’s IPO filing. On September 28, all three major equity indexes closed lower, with semiconductors and optical communications among the sectors that retreated. Anthropic’s filing showed high growth alongside large losses and $518 billion in cloud commitments. Its tokenized share traded near $2,002, down about 2% in 24 hours. Spot gold approached a two-month low near $4,118, while Bitcoin traded near $83,500.
Contents
Latest articles


Latest coin listings on WEEX


